Showing posts with label Poh Huat. Show all posts

Saturday, 12 December 2015

Poh Huat (5)

Target Price of RM3.50 According To Conspiracy Theory ?

Author: Icon8888   |   Publish date: Mon, 27 Jul 2015, 03:21 PM 


1. Conspiracy Theory

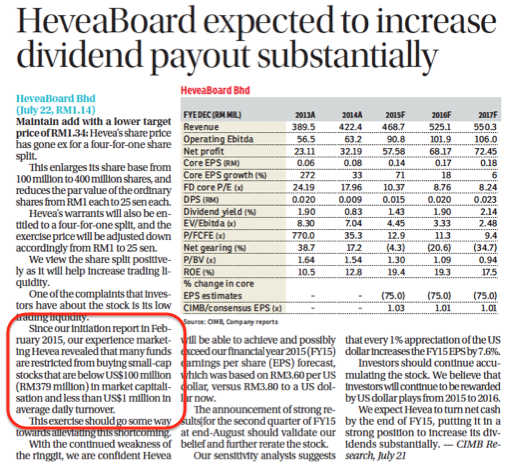
According to CIMB's analyst report dated 22 July 2015 for Hevea, a lot of funds cannot buy stocks with daily trading volume lower than RM1 mil (RM3.8 mil).

This could be one of the reason why recently some public listed companies, backed by strong earnings, decided to undertake bonus issue and / or share split. Far from a superficial exercise, this should lead to higher trading volume and put them in Fund Managers' radar. 


Before the share split, Hevea has trading volume of approximately 0.8 mil shares. Based on share price of let's say, RM3.70, daily trading volume will be 0.8 m shares x RM3.7 = RM2.96 mil, less than RM3.8 mil.

However, after split, trading volume reached 8.72 mil shares in the first trading day. Based on RM1.00 then, trading volume was RM8.72 mil, above the RM3.8 mil threshold.

In addition, according to CIMB, a lot of funds also cannot buy stock with market cap less than USD100 mil (RM380 mil). Hevea has 100 mil shares before split. If they target to attract funds, share price has to be at least RM3.80. 

On 20 July 2015, one day before the share split went ex, Hevea closed at RM3.79 !!!!

Was that just a coincidence or due to support by invisible hands ? I think only those people behind it have the answer.
  
It seemed that the tricks worked. With RM380 mil market cap, the moment the stock went ex the next day, there was aggressive buying, pushing share price from RM0.95 to RM1.05. Since then, share price sustained at around RM1.10, equals to RM4.40 before split.

Funds buying ? As usual, I don't have the answer.
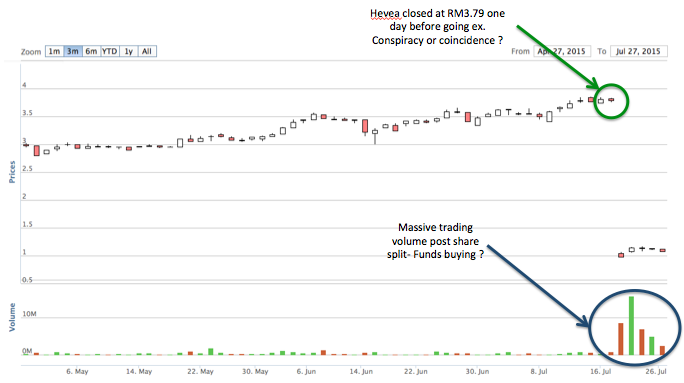

(Coincidence or conspiracy ?)


2. Poh Huat 's Rising Share Price

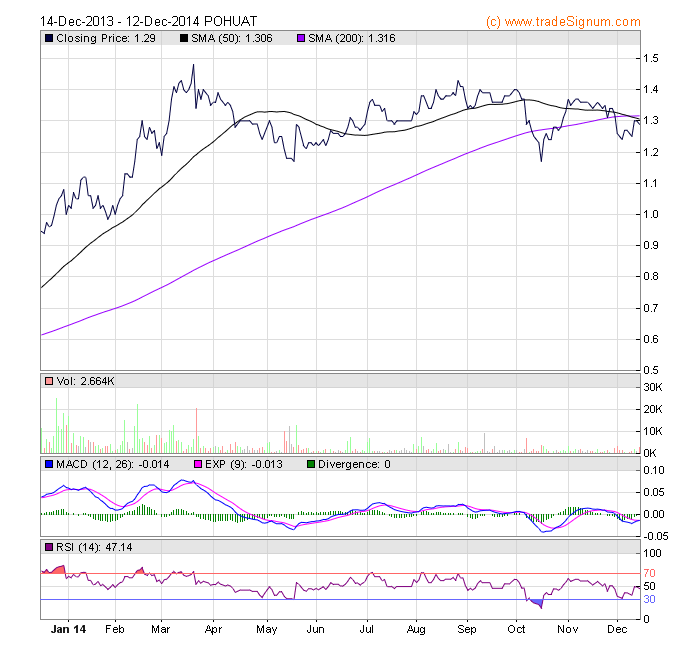
Recently, Poh Huat share price has performed very well, rising from RM2.18 on 10 July to RM2.80 on 27 July, a gain of 28% over 2 weeks.

This has sent tongues wagging on whether a bonus issue or share split is imminent.


With the Hevea conspiracy in mind, I decided to do a quick check on how things will pan out if the same plot is applied to Poh Huat. 

Based on Poh Huat's 107 mil shares, share price of RM3.50 will result in RM380 mil market cap. 

How will Poh Huat look like at RM3.50 ? 

During the financial year ended October 2014, Poh Huat reported net profit of RM23.8 mil. However, as pointed out in my past articles, their July 2014 quarter was adversely affected by riot in Vietnam. Based on rough estimate, without that distorting effect, net profit could be approximately RM28.5 mil. 

That was when USD / RM exchange rate was about RM3.20. The exchange rate now is RM3.80.

It is not inconceivable that Poh Huat can deliver RM35 mil net profit in the latest financial year, boosted by strong US dollar as well as better economic performance of Uncle Sam, its major customer.

At RM3.50, PER will be a comfortable 10 times.


3. Concluding Remarks

(a) First of all, I declare that I am a shareholder of Poh Huat. So I will be positively biased as far as its prospects is concerned. Please take whatever I said with a pinch of salt.

(b) I don't expect anybody to be so reckless / silly to rush in to buy Poh Huat at this price so as to benefit from "further upside" at RM3.50. Afterall, it is just a conspiracy theory.

(c) I wrote the article mostly for fun. At the end of the day, I expect share price to be driven by earnings and dividend, instead of corporate exercise like bonus issue / share split. Maybe Poh Huat will go RM3.50, maybe it won't. Please don't blame me if things don't work out as expected. 

Poh Huat (4) - Re-Rating Might Happen Sooner Than Expected


Author: Icon8888   |   Publish date: Sat, 11 Jul 2015, 01:06 PM 


Compared to other furniture stocks, Poh Huat's share price has not been so dynamic.

I believe this is due to perception that Poh Huat's business is seasonal.

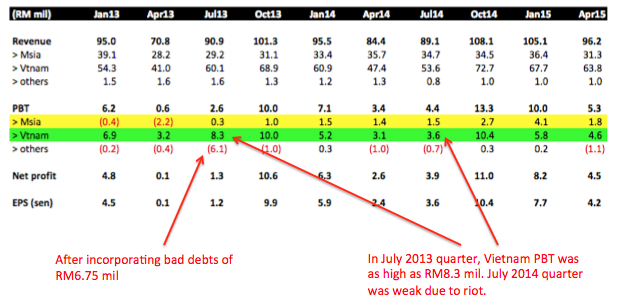
Referring to table below, many people would have concluded that October and January are strong quarters, while April and July are weak quarters.


If that is true, then the coming July quarter results, to be released by end September 2015, will continue to be weak. Excitement will only come in by end of December 2015 (6 months from now) when the October quarter is released.  

As such, many people feel that the stock is unlikely to go anywhere from now until December 2015. 

With that perception, no wonder Poh Huat share price has been lethargic. 

However, as I took a closer look at Poh Huat's historical figures, I discover that this is not necessarily the case.

Contrary to popular belief, Poh Huat only has ONE weak quarter (the April quarter that was just released last week). The coming July quarter will be strong.  

The reason is because the FY2013 July quarter was distorted by provision of bad debts of RM6.75 mil while the FY2014 July quarter was distorted by riot in Vietnam, which adversely affected Poh Huat's operation.


(Angry crowd is bad for business)

It was just a conincidence that in both years, certain bad things happened during July quarter !!!


Without those exceptional items, July quarter net profit for FY2013 and FY2014 would have been RM9.35 mil and RM9.8 mil, translating into EPS of 8.3 sen and 8.7 sen respectively.

Compared to FY2013 and FY2014, this coming July quarter result will be boosted by the following :-

(a) Weakening of Ringgit   In FY2013 and FY2014, Ringgit / USD was 3.13 and 3.27. In July 2015 quarter, the exchange rate was easily 3.65.

(b) Turning Around of Malaysian operation   In July quarter of FY2013 and FY2014, Malaysia operation generated PBT of RM0.3 mil and RM1.5 mil respectively. With revamping of its operation, Malaysia division nowadays generates PBT of RM2 to RM4 mil easily.

However, tax rate could be higher. In latest quarter ended April 2015, tax rate was 17% instead of zero.

Taking all these into consideration, it is not inconceivable that Poh Huat's coming July quarter EPS could be closed to 10 sen. 

With share price at RM2.19, that kind of EPS should get many people excited and trigger a re-rating.

Bountiful harvest is near. Enjoy the fruits of your investment.


Poh Huat (3)

Time To Load Up

Author: Icon8888   |   Publish date: Tue, 2 Jun 2015, 03:15 PM


Poh Huat will release its April 2015 quarterly results by end of this month (June 2015). Traditionally, April and July quarters are weak while October and January quarters' net profit are almost 100% higher.

The seasonality of net profit is primarily related to its Vietnam operation, which exports home furnitures to the US, the demand of which is strongest in the October and January quarters.

However, in latest two quarters, the Group's Malaysian operations had turned around substantially pursuant to internal restructuring.

Previously with PBT of only RM1 mil plus, the Malaysian division reported PBT of RM4.1 mil in January 2015 quarter, narrowing the gap with its Vietnam division.

The Malaysia division exports office furniture primarily to Canada. Unlike sales to US, this division is not so affected by seasonality. 

In my opinion, the higher weightage of the Malaysia division's contribution to proftibility will help to smooth out the seasonality effects traditionally associated with Poh Huat. In other words, there is likelihood that the coming quarter result will not be as weak as previous years.


(RM mil)Jan13Apr13Jul13Oct13Jan14Apr14Jul14Oct14Jan15
Revenue95.070.890.9101.395.584.489.1108.1105.1
> Msia39.128.229.231.133.435.734.734.536.4
> Vnam54.341.060.168.960.947.453.672.767.7
> others1.51.61.61.31.21.30.81.01.0
PBT6.20.62.610.07.13.44.413.310.0
> Msia(0.4)(2.2)0.31.01.51.41.52.74.1
> Vnam6.93.28.310.05.33.13.610.45.8
> others(0.2)(0.4)(6.1)(1.0)0.3(1.0)(0.7)0.30.2
Net profit4.80.11.310.66.32.63.911.08.2
EPS (sen)4.50.11.29.95.92.43.610.47.7


Friday, 7 August 2015

Poh Huat (1)

Beneficiary of Weak Oil Price

Publish date: Sun, 14 Dec 2014, 08:01 PM 


Executive Summary

(1) Furniture exporter with approximately 90% sale to US.

(2) PER of 6.8 times based on historical EPS of 19 sen. 

(3) Weakening of Ringgit from RM3.12 to RM3.50 per USD could propel EPS to 48 sen ? 

(4) Paid out 8 sen dividend in 2014, equivalent to dividend yield of 6.2%

(5) October quarterly result will be released soon. Traditionally strongest quarter due to year end festive season sales.


1. Introduction

Poh Huat is a furniture manufacturer with factories in Johor and Vietnam. Almost all its products are exported to US.

Based on latest closing price of RM1.30 and shares outstanding of 113 mil, market cap is RM147 mil.

Based on historical net profit of RM22 mil, PER is approximately 6.8 times.

Based on net assets of RM164 mil, PBR is approximately 0.9 times.

Healthy balance sheet with small net cash (RM47 mil loans backed by RM51 mil cash).


2. Hsitorical Profitability


FY2013YTD
(RM mil)Jan 13Apr 13July 13Oct 13TotalJan 14Apr 14July 14Total
Revenue95.070.890.9101.3358.095.584.489.1269.0
> Malaysia39.128.229.231.1127.633.435.734.7103.8
> Vietnam54.340.960.168.9224.260.947.453.7162.0
> others1.61.61.71.36.21.21.20.83.3
PBT6.20.62.610.119.57.13.44.414.9
> Malaysia(0.4)(2.2)0.3n/an/a1.51.41.54.4
> Vietnam6.93.28.3n/an/a5.33.13.611.9
> others(0.2)(0.3)(6.75) ^n/an/a0.3(1.1)(0.7)(1.5)
Net profit4.80.21.310.316.66.32.53.812.5
EPS (sen)4.20.21.19.114.65.52.23.311.0
USD : RM3.0533.0853.1173.2333.1223.2503.2823.2103.247

^ bad debt related to Poh Huat Qingdao, a small subsidiary which has since been disposed of 


(a) Reported net profit of RM16.6 mil in FY2013. However, there was a bad debt ofRM6.75 million. Excluding that exceptional item, net profit would be RM22 mil.

(b) Reported net profit of RM12.5 mil for 9 months ended July 2014. However, the July 2014 quarterly result was adversely affected by riot in Vietnam. In the July quarter for FY2013, Vietnam division reported PBT of RM8.3 mil. Due to the riot, July 2014 quarter Vietnam PBT was only RM3.6 mil.

If we assume that the July 2014 Vietnam PBT is same as FY2013, YTD nine months net profit would be RM16 mil (instead of RM12.5 mil). Based on assumption that the coming October 2014 quarter also reported net profit of RM10.3 mil (same as Oct 2013 result), FY2014 net profit would be RM26.3 mil. Prospective PER based on sustainable earnings would be approximately 5 times.

(c) For FY2013, average RM : USD exchange rate is RM3.122.
For 9 months ended Oct 2014, average exchange rate is RM3.247.
As at to-date, exchange rate is RM3.495.


3. Dividend Yield of 6.2%

In calender year 2014, the Company has so far declared 8 sen dividend (2 sen yet to go ex). 


Based on share price of RM1.30, dividend yield is 6.2%.


Date of
announcementDetailsamountEx date
31 Oct 2014Second interim2 sen6 Jan 2015
10 Sept 2014First interim 3 sen 8 Oct 2014
1 April 2014Final3 sen7 May 2014
Total8 sen
28 Nov 2013Special2 sen11Dec 2013
3 April 2013First and final2 sen7 May 2013
Total4 sen

(source : Bursa website)


4. Net Profit Sensitivity Analysis

With its revenue denominated in USD, every single sen increase in revenue due to Ringgit devaluation will flow directly to net profit after deducting 25% tax (assuming that this is the effective tax rate).

Based on simplistic financial modelling, the group's net profit will increase as follows when the Ringgit weaken :-


FY2013RM:USDRM:USDRM:USDRM:USD
3.123.303.503.70
Revenue358.0378.7401.6424.6
Net profit21.637.154.3 #71.6
EPS (sen)19.232.948.163.3
PER (x)6.84.02.72.1


# To understand how I arrived at the figures, let's take RM : USD 3.5 as example :-


(1) FY2013 revenue of RM358 mil was arrived at based on USD : RM of 3.12

(2) If Ringgit depreciates to 3.5, revenue will be RM358 mil x 3.5 / 3.12 = RM401.6 mil

(3) the surplus of RM43.6 mil will flow directly to pretax profit

(4) After deducting 25% tax, net gain will be RM32.7 mil

(5) Net profit will be RM21.6 mil + RM32.7 mil = RM54.3 mil


5. Concluding Remarks

(1) I am not the first one to suggest that weak Ringgit will benefit exporters. For example, The Edge Financial Daily has recently proposed buying into Homeritz exactly for that purpose. However, I had gone one step further to try to quantify the benefit through financial simulation.

(2) Before you jump into the market to buy up Poh Huat big time, let me qualify that if you ask me whether I really believe that Poh Huat will increase its net profit next year by 150% to RM54.3 mil, my answer is "Probably not...". 

My reasoning is very simple. In life, you will seldom be rewarded so handsomely without trying real hard. 

Unless Poh Huat has already locked in next year revenue in USD through contractual arrangement (which I doubt so), I would expect the American purchasers to demand downward revision of USD pricing once they get wind of the windfall gain arising from the Ringgit devaluation.

Having said so, I don't think they will be so unreasonable as to wipe off the entire gain (afterall, are they going to compensate Poh Huat in the opposite case of Ringgit strengthening ? I don't think so).   

I believe there will be actual substantial translation gain in the event that the average USD : RM exchange rate next year is 3.5. For example, a 50% increase in net profit is not inconceivable.


(3) Apart from weaker Ringgit, the collapse of oil price has put more money into Americans' pockets. With more spending power, demand for furniture will also go up (hey, let's change our sofa now that we are saving so much money from lower fuel price). That is why the title of this article is "Beneficiary of Weak Oil Price" instead of just "Beneficiary of Weak Ringgit".


(4) If you are thinking of buying into Poh Huat after reading this article, please be warned that in a market meltdown like in 1997, all share price will collapse no matter how profitable a company is. The market will simply go insane.

So please be careful with your money. Think hard before you jump in.

Have a nice evening.