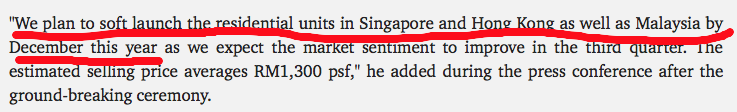Wednesday, 10 January 2018

CIMB (3) - Taking A Peek At Coming Quarter Result

Author: Icon8888   |    Publish date: Sun, 14 Aug 2016, 03:10 PM

1. Introduction

After I published Part 2 on 30 July 2016, a sharp eye reader made an interesting observation. He pointed out that the profitability of CIMB Non Niaga (namely Malaysia, Thailand and Singapore operations) has been on downward trend (down from RM778 mil to RM752 mil to RM731 mil). 
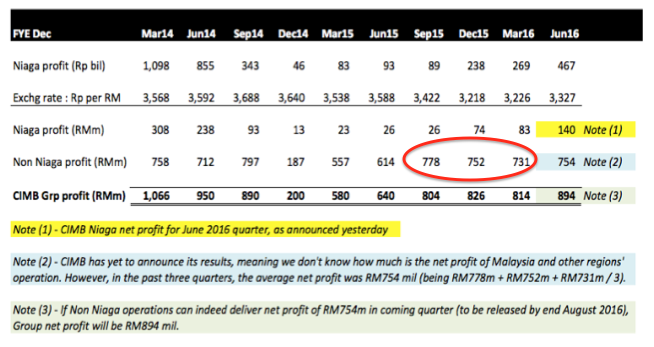
(Note : the above table is extracted from Part 2)

Is Non Niaga's decline in profitability structural in nature ? This is an important question.

CIMB Niaga's recently released June 2016 quarterly result showed improvement. However, if Non Niaga's profit is indeed on "downward trajectory", the coming quarter overall result (to be released by end August 2016) might not be good.

To find out the answer, I decided to perform a more detailed analysis of the CIMB Group's past few quarters' performance.


2. Non Inerest Income Is The Main Culprit

When I started my analysis, I intended to study three quarters : September 2015, December 2015 and March 2016. However, after taking a closer look, I noticed that the September 2015 quarter included expenses incurred for the Mutual Separation Scheme. The figures were quite messy and it is difficult to figure out how the entire CIMB Group has actually performed in that quarter. As such, I narrowed down my study to only the December 2015 and March 2016 quarter.
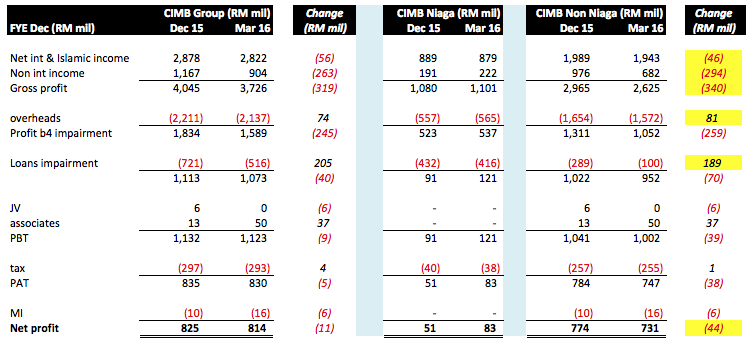

Key observations :-

(a) As mentioned above, Non Niaga's profit declined from RM774 mil in December 2015 to RM731 mil in March 2016, a decline of RM44 mil. What caused the decline ?

(b) Net interest income and Islamic banking income, which form the backbone of banking operations, was quite stable. There was a small decline of RM46 mil. In my opinion, that was not really that material.

(c) The biggest drop was actually caused by Non Interest Income, which declined by a whopping RM294 mil.

(d) As a result of the above, Gross profit declined by RM340 mil.

(e) Fortunately, Non Niaga's other operational parameters mostly improved. Overheads were reduced by RM81 mil while Loan Impairment was RM189 mil lower than previous quarter, collectively resulted in saving of RM270 mil.

(f) That helped to offset the bulk of the weakness seen in Non Interest Income.

Now that we have established that Non Interest Income is the main culprit, the next step is to find out what constitute Non Interest Income and whether it will continue to be weak in coming quarter.  


3. Non Interest Income
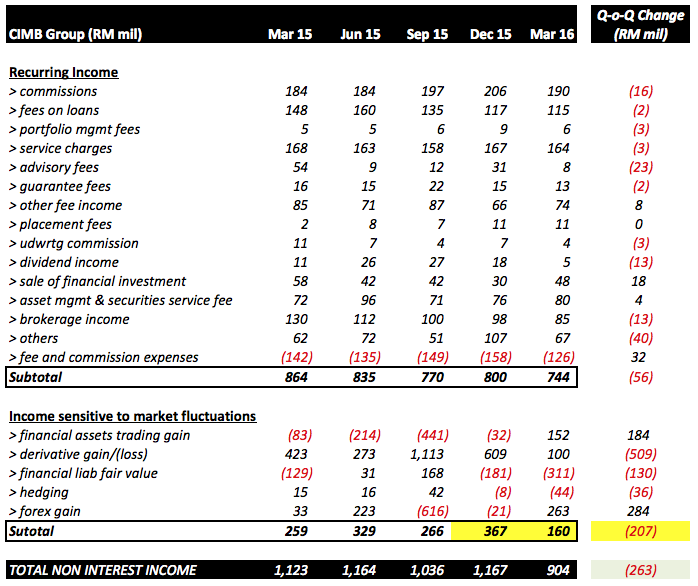
 

Key observations :-

(a) CIMB provides detailed breakdown of its Non Interest Income. Pursuant to my analysis, they can be grouped under two major categories : (i) Recurring Income and (ii) Income sensitive to market fluctuations.

(b) Recurring Income includes those items such as commissions, advisory fees, brokerage income, etc. Please go through the list in the table above, which is self explanatory.

(c) Income Sensitive To Market Fluctuations comprise 5 major items :-
(i) financial assets trading gain;
(ii) derivative trading gain;
(iii) fair valuation of financial liabilities;
(iv) hedging; and
(v) forex gain.

(d) Unlike Recurring Income, these items are volatile in nature. For example, forex trading incurred a loss of RM616 mil in September 2015 and chalked up RM263 mil gain in March 2016.

(e) But please don't get me wrong. I am not saying that CIMB (or any other bank) engages in risky speculation. Banks are regulated by BNM. I am pretty sure that whatever they do, they must have done it with proper risk management measures in place. 

You can actually see this through the combined figures. Despite huge swing of individual components, collectively these items generated profit within a narrow band of RM259 mil to RM367 mil. 

(f) However, it seemed that luck was not on their side in the March 2016 quarter. Profit deviated substantially from the narrow band. That was mostly caused by larger than normal fair value loss for financial liabilties (RM311 mil, I have no idea what that is) and lower derivative gain (RM100 mil only, as compared to RM609 mil in previous quarter). 

The end result was that Non Interest Income declined by RM263 mil.  


4. Concluding Remarks

According to my analysis, the Q-o-Q decline in Non Niaga's profitability (comprises Malaysia, Thailand and Singapore operations) was not structural in nature. It was mostly caused by unfavorable luck factor in March 2016 quarter. 

CIMB Niaga has already delivered a positive set of results recently. We are holding our breath, waiting to find out whether the other divisions can also perform well and deliver a strong set of results for the entire group.

Best of luck to all CIMB shareholders.

Crest Builder (2) - 2017 Will Be An Interesting Year

 Author: Icon8888   |    Publish date: Thu, 11 Aug 2016, 12:06 AM

1. Introduction

I first wrote about Crest Builder in May 2014. 

The stock recently caught my attention again because it secured RM438 mil new contract from Sime Darby. I did a quick study of the Group and found a few interesting points. There is a possibility that the stock could be re-rated in 2016 and take off in a big way in 2017. Please read on.


2. Background Financials

Crest Builder is principally involved in construction and property development. It also holds 51% equity interest in a 23 year government concession (ending 2034) to construct and maintain Universiti Teknologi Mara in Tapah, Perak.    

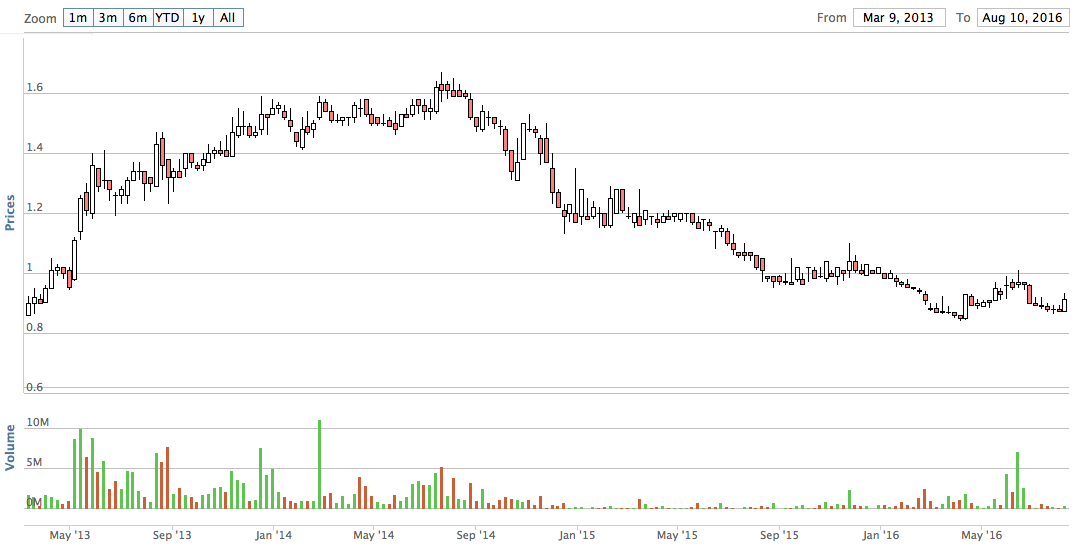
Based on 177 mil shares and latest closing price of 92 sen, Crest Builder has market cap of RM163 mil.

In my opinion, the group is quite well run, as evidenced by its uninterrupted profitability since at least 2003.

F.Y.Revenue ('000)Profit Attb. to SH ('000)EPS (Cent)PEDPS (Cent)DYNAPS
2015-12-31283,94410,4116.2016.464.003.922.3000
2014-12-31207,39220,75612.8010.553.752.782.3500
2013-12-31223,40448,76732.604.793.752.402.2900
2012-12-31485,06721,58516.605.255.005.752.1800
2011-12-31499,84930,42324.602.045.0010.002.1600
2010-12-31460,07913,93911.304.704.007.551.9400
2009-12-31329,56410,9878.906.753.005.001.8600
2008-12-31270,27512,34310.003.303.009.091.7900
2007-12-31365,76640,19332.503.027.007.141.7500
2006-12-31318,26620,03416.404.765.006.411.4600
2005-12-31253,00611,74010.306.024.006.451.3400
2004-12-31266,29116,26414.304.624.006.061.2800
2003-12-31205,31617,47218.605.764.003.740.5141


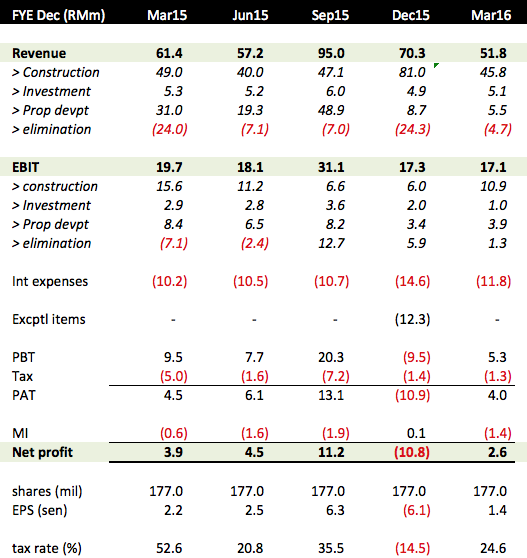
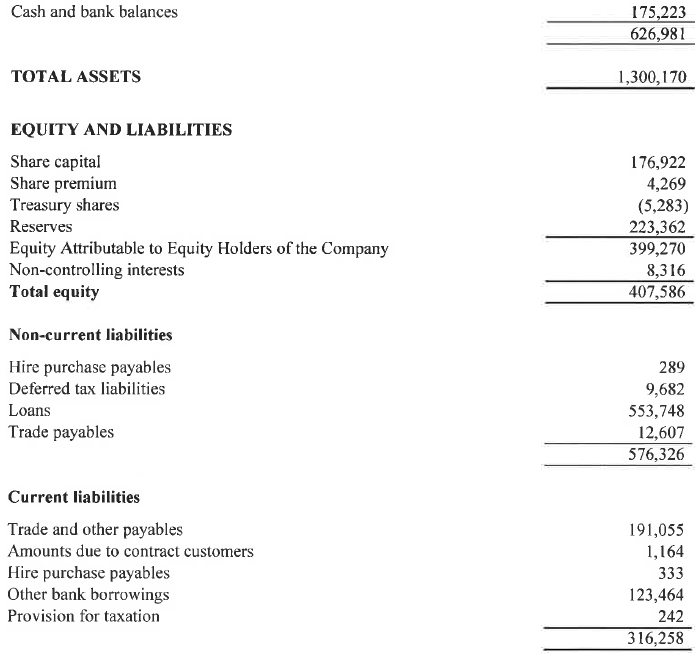
As at 31 March 2016, the group has net assets of RM399 mil and loans of RM677 mil. The actual gearing is not as alarming as it looked. Closed to RM500 mil of the borrowings are related to the Universiti Teknologi Mara concession. Actual borrowing is approximately RM177 mil, which translates into gearing of 0.44 times (I have been conservative by ignoring its cash holding of RM175 mil).


3. King Of TODs

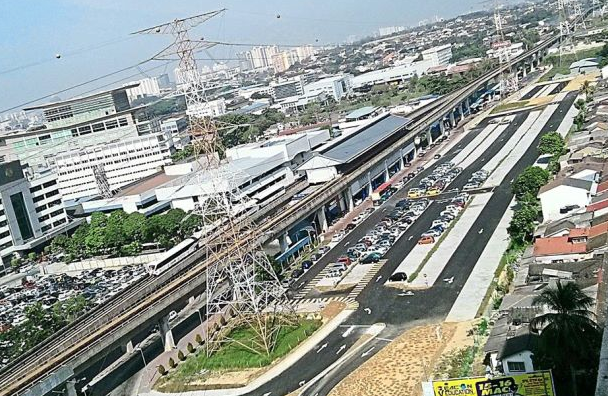
TOD stands for "Transit Oriented Development". In Malaysia, it is a term used to describe property projects located within the compound of LRT stations. Prasarana, being the owner of the LRT station land, enters into joint venture with developers to construct commercial and/or residential properties on the site. In return, Prasarana will get certain percentage of the Gross Development Value by cash or payment in kind (property units).

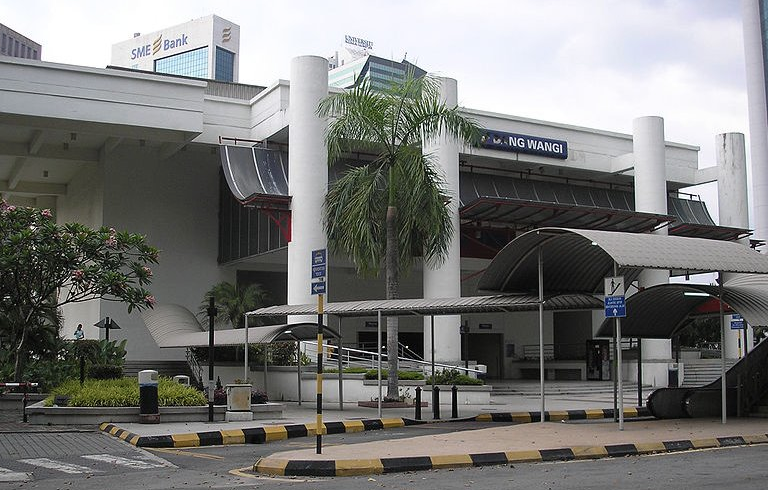
Around 2012, Prasarana awarded several TODs to developers. Crest Builder managed to secure two : one at Dang Wangi LRT Station and the other one at Kelana Jaya LRT Station. 

(Dang Wangi LRT Station, Jalan Ampang, KL)

(Kelana Jaya LRT Station, PJ)

However, the projects had been very slow to get off the ground. Prasarana needs to go through various government departments to secure the requisite approvals. 

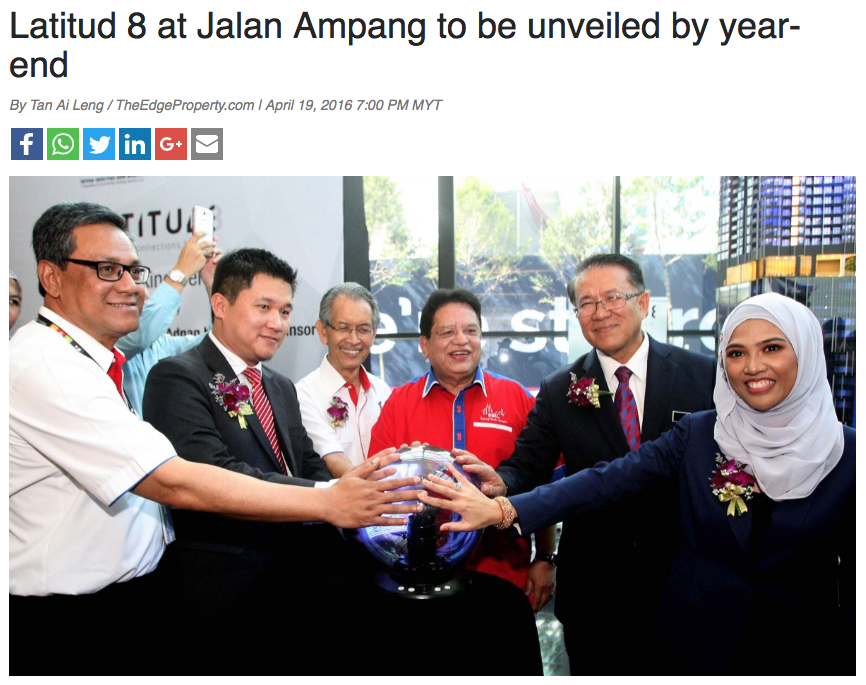
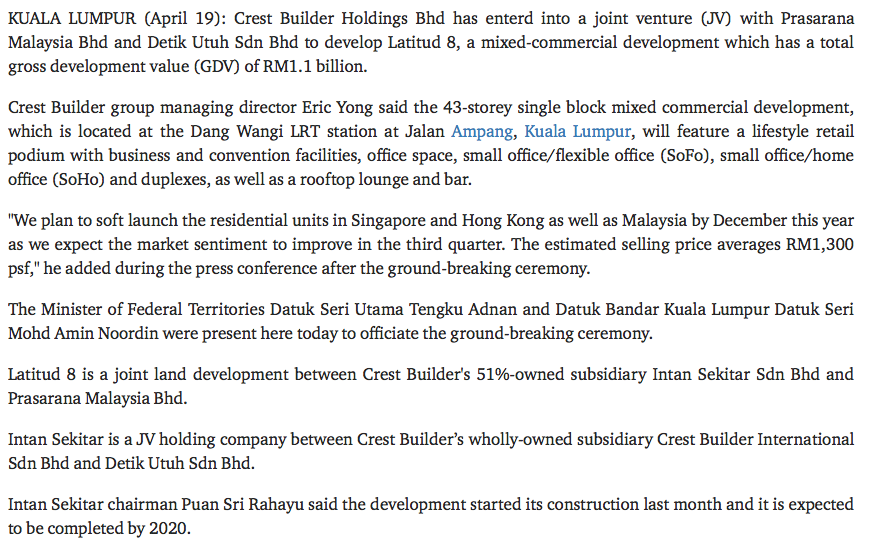
Finally, on 19 April 2016, Crest Builder and its partner Detik Utuh Sdn Bhd entered into formal agreement with Parasarana to finalise the Dang Wangi project (the Kelana Jaya JV yet to be finalised).


As mentioned in article above, they target to launch the residential units in Malaysia, Singapore and Hong Kong by December 2016. 


THAT, actually is not sufficient to get me excited. If they launch the units by end 2016, it will easily take another one to two years before they can start booking in profit (progress billing). It is too early to buy this stock if you are aiming for development profit.      

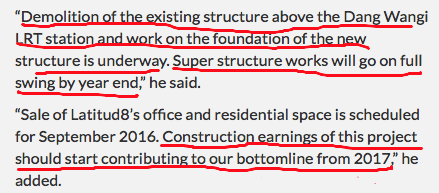
However, the article above also mentioned that they "have started construction last month". The story has now become much more interesting. 


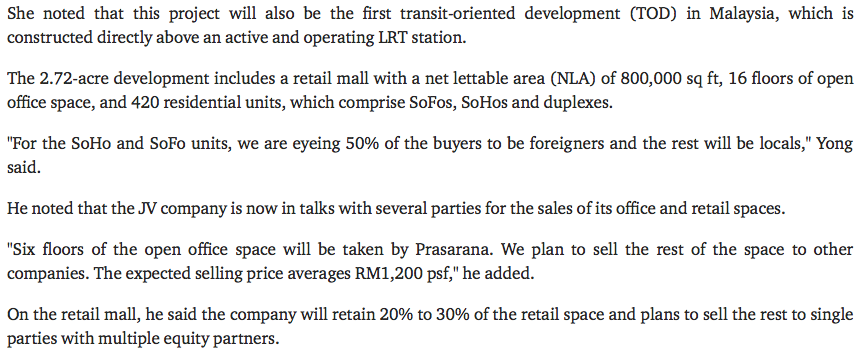
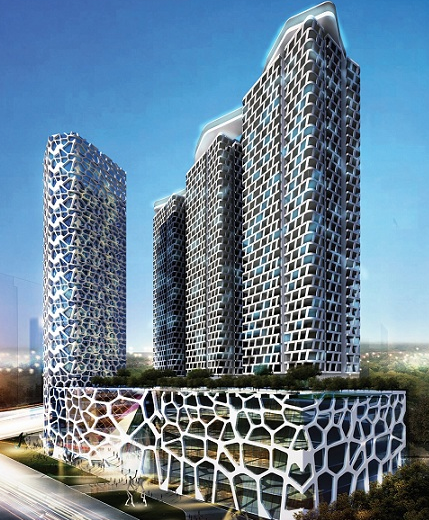
Crest Builder has a property development division. All this while, the construction works are all done in house (as disclosed in their financial statements). It turns out that it will also be the contractor for the Dang Wangi project. 

(Source : New Straits Time 30 May 2016)

According to the Company, construction profit will start contributing to bottomline in 2017.

THIS IS POSITIVE POINT #1.

(Please note that the Dang Wangi project is not wholly-owned by Crest Builder. As such, the construction profit is real, not something to be eliminated upon consolidation).


4. Potential Disposal of Investment Property

After finalising the JV agreement in April 2016, the next step is to sort out financing for the construction works. 

Crest Builder is currently in talks with investors to come in as equity partners for the Dang Wangi project. On top of that, it is also in discussions with potential buyers to dispose of its investment property Tierra Crest.

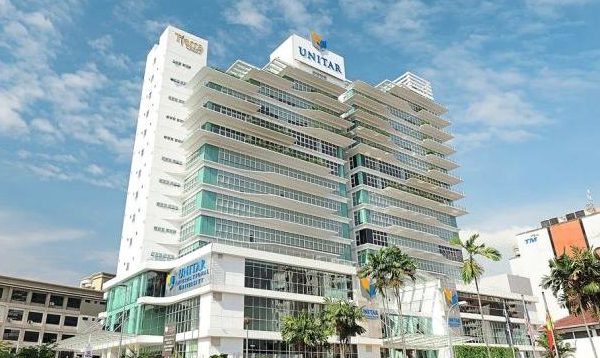
(Tierra Crest is located in Kelana Jaya. In 2012, Crest Builder secured a nine year tenancy agreement with Unitar International University)

(Source : New Straits Time)

I strongly believe that Crest Builder will dispose of the property as mentioned above. The group is currently in growth mode. It doesn't make sense to hold on to investment property for small amount of recurrent income. Apart from the Dang Wangi project, the group will be launching Galleria @ Jalan Ampang in 2017. It is a JV project with (again) Detih Utuh Sdn Bhd and Lembaga Getah Malaysia (more details below). 

The disposal, if materialised (very likely over next few months), will trigger a re-rating. 

THIS IS POSITIVE POINT #2.


5. Healthy Order Book

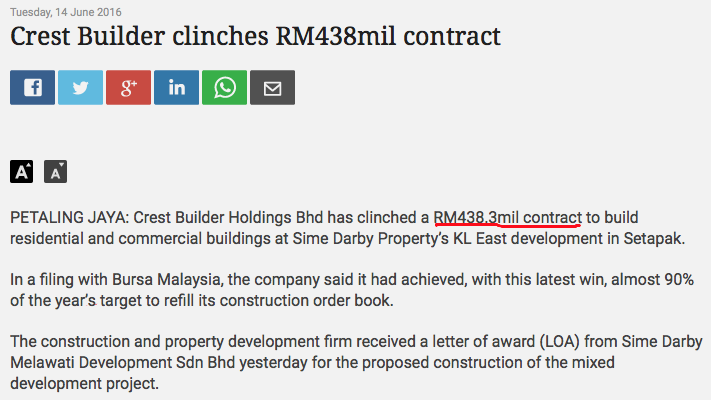
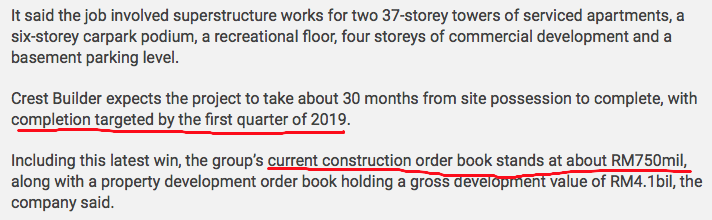
On 14 June 2016, Crest Builder announced that it has secured RM438 mil construction contract from Sime Darby. This boosted its order book to RM750 mil.  


The size of the order book might not be big if compared to other major players. However, in FY2015, Crest Builder's construction revenue was only RM106 mil. As such, RM750 mil should be sufficient to last them at least two to three years (the group is currently tendering for RM4.5 billion contracts).   

THIS IS POSITIVE POINT #3.


6. JV With Lembaga Getah Malaysia

  
(Galleria @ Jalan Ampang, to be launched in 2017 and has GDV of RM1.3 billion. The land is owned by Lembaga Getah Malaysia and is located opposite Great Eastern Mall at Jalan Ampang, near MRT station)

On 28 June 2012, Crest announced that its 51% subsidiary has entered into JV agreement with Lembaga Getah Malaysia to develop 5 acres of land at Jalan Ampang, opposite Great Eastern Mall and next to Gleneagles Hospital.

The proposed development will comprise three 28 storey Apartments and SOHO Towers, a 33 storey Corporate Tower and a 6 storey retail mall (note : details subject to changes).

GDV is estimated to be RM1.3 billion. LGM will be entitled to RM300 mil (22.5%), in cash and completed property.

Based on latest update, the Galleria is scheduled for launch sometime in 2017.


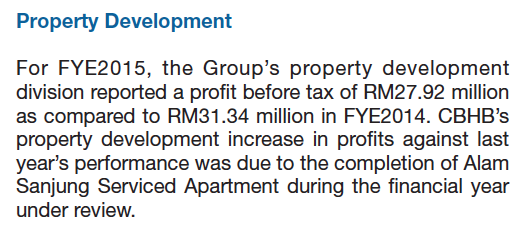
7. Other Development Projects

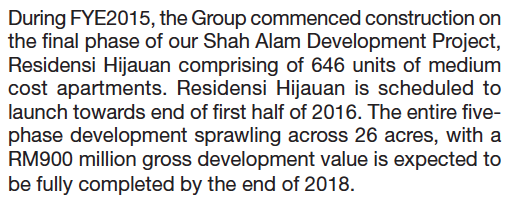
(Source : FY2015 annual report)


8. Shares Buy Back

Since August 2015, the company has been consistently buying back shares (6 mil shares so far).

This active support by the company gives me a lot of comfort, and is one of the main reasons I bought into the stock. I believe downside is limited, while there is potential upside as early as 2016 / 2017. 


TRC Synergy - Flushed With New Contracts, But Execution Is Key

Author: Icon8888   |    Publish date: Mon, 15 Aug 2016, 10:27 AM


1. Introduction

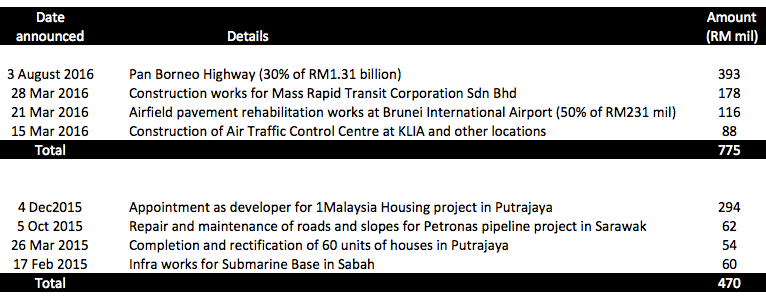
TRC is principally involved in construction and property development. It attracted my attention because recently its 30% owned JV vehicle secured a RM1.31 billion construction contract for Pan Borneo Highway (effective interest of RM393 mil). 


2. Background Financials

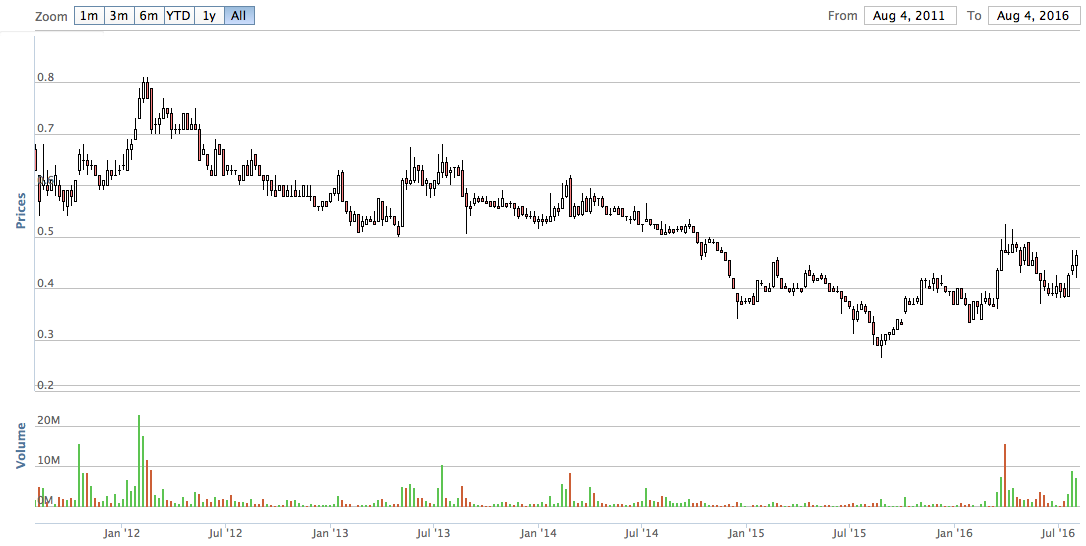
Based on 480 mil shares and market price of 46 sen, market cap is RM221 mil. 

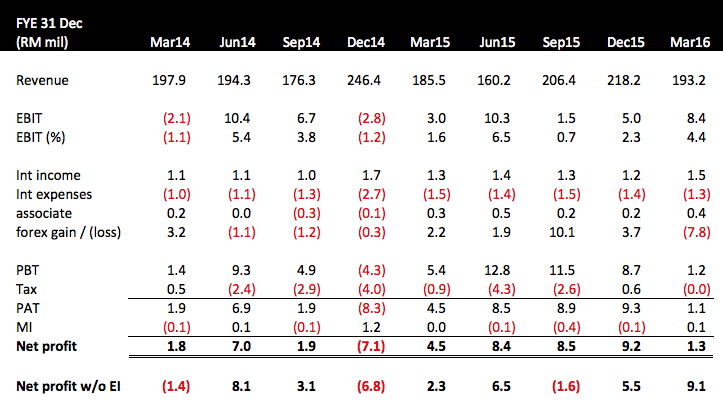
The group reported aggregate net profit of RM27 mil in past twelve months. As such, historical PER is approximately 8.2 times.

The group has net assets of RM357 mil, borrowings of RM193 mil and cash of RM198 mil. As such, it is in net cash position of RM5 mil.


3. Historical Profitability


Key observations :-

(a) At first look, the group has done well in past few quarters. However, upon closer examination, the bulk of the profit (RM18 mil out of RM31 mil in FY2015) was due to forex gain. 

(b) In the March 2016 quarter, the group's net profit declined to RM1.3 mil. However, that was due to forex loss of RM7.8 mil. Without that, the group has actually done well with core earning of RM9.1 mil, translating into EPS of 1.9 sen.


4. Flushed With New Contracts

2016 is a bumper year for the group. It secured one contract after another. Please refer to table below for details.


5. Transit Oriented Development Project At Ara Damansara

In 2013, TRC entered into JV agreement with Prasarana for the mixed development project at LRT Station 2 at Ara Damansara, PJ. GDV is estimated to be RM1 billion. After finally resolving land transfer issue, the group targets to launch the project in first quarter 2017.


6. Concluding Remarks

TRC is very good at replenishing its order book. However, I have a bit of reservation about the stock as its past profit has been erratic. 

I have bought a little bit and will only buy more if coming quarter result is good. 

Saturday, 30 July 2016

CIMB (2) - CIMB Niaga Profit Up 74%. Buy Lah, Wait For What ?

Author: Icon8888   |   Publish date: Sat, 30 Jul 2016, 02:41 PM 

1. Introduction

Yesterday, CIMB Niaga released its June 2016 quarterly report. There was marked improvement in results. Net profit increased by 74% Q-o-Q. 

(Press release spinned it as 318% increase Y-o-Y. However, I think Q-o-Q is more reflective of its latest earning momentum)


2. Results Analysis


(a) Compared with previous quater, net profit increased by 74% to Rp467 bil.


(b) One of the major positive contributor is Net Interest Income, which increased by Rp139 bil compared to previous quarter. The increase is mostly due to decline in interest expenses from Rp2,552 bil in previous Q to Rp2,246 bil (decline of Rp306 bil), mostly due to increase in Current Account Deposit. Net interest margin improved from 53% to 57%. Well done !!!   

(c) The other major contributor is lower impaired loans provision, which resulted in saving of Rp120 bil. This is the second consecutive month of decline, after peaking in December 2015 quarter.

Provision is expected to continue to decline in coming quarters as CIMB CEO hinted in a recent interview that he expects second half of 2016 to perform better. Please refer to my previous article for details.

(d) Operating expenses increased by Rp25 bil. This was a negative surprise. After the mid 2015 Mutual Seperation Scheme, I expect cost to come down, not go up. Anyway, it is not a big issue as the increase is not really that big.


3. Earning Forecast

In my previous article, I have guarded feelings for the CIMB Group. I sensed that they are turning around, but was not sure when the recovery will actually take place. However, with CIMB Niaga announcing a reasonably good set of results yesterday, I have turned much more positive towards the group.

Armed with this new piece of information, I set up a financial model to try to feel the CIMB Group's coming quarter result. 


Many people frown upon building financial model to predict future earning. Garbage in garbage out, if you get your assumptions wrong, your prediction will be way off.

However, in this particular case, there is sufficient ground for making such an attempt - the performance of CIMB's non Niaga operation has been fairly stable. In the past three quarters, it has generated net profit of RM778 mil, RM752 mil and RM732 mil respectively. I believe there is reasonable chance that the coming quarter will be more or less the same.

By putting together the above information, the model estimates that coming quarter net profit will be approximately RM894 mil.

But how should we interprete this figure ? What is the implication on valuation ? In other words, what should be the Target Price ? 


4. Target Price

I previously set a Target Price of RM5.20 for the stock. That was plucked from the air based on my entry cost of RM4.29 and expected return of 20%.

However, now that I have a better feel of the Group's positive momentum, I am happy to revise it upwards. For inspiration and guidance, I looked back to early 2014 when CIMB was still doing well.


As shown in the diagram above, CIMB traded at RM7.30 based on quarterly profit of RM1.066 bil in March 2014. The coming quarter of RM894 mil predicted net profit, if materialised, will be approxmimately 84% of its March 2014 quarter profit.

By applying 16% discount to RM7.30, I arrived at revised Target Price of RM6.13 for CIMB over the next 12 months.

This represents potential upside of 40% over latest closing price of RM4.39.


5. Concluding Remarks

(a) Among all the banking stocks, I believe CIMB has the best long term growth potential. This is because of the relatively high weightage of its Indonesian operations. Indonesia's GDP per capita is still low and its population is huge. The country will conitnue to grow at a brisk pace for many years to come, dragging CIMB along with it.
(b) The Group's past 12 months performance was disastrous. Its exposure to Indonesia became a big liability, dragging down its overall profitability as Indonesia floundered under the tremendous downward pressure caused by collapse of commodity prices.

(c) However, this weakness has now become its strength. From investing point of view, CIMB has bigger upside potential compared to other banking stocks such as AFG, Public Bank, Hong Leong Bank, BIMB, etc, which have done reasonably well operationally.

(d) With the Indonesian economy now gaining strength, I believe we have reached an inflexion point for CIMB. The risk and reward ratio going forward looked favorable. It is time to stop sitting on the fence.

Buy lah, wait for what ?